Buying a home is exciting. You start imagining a kitchen where you can cook your favorite meals, a backyard for weekend gatherings, or a comfortable space to call your own. But before you fall in love with a property, there is one important question to answer: How much house can you actually afford without stretching your budget too thin?
For many homebuyers, figuring out an affordable home price can feel overwhelming. Mortgage rates, monthly payments, property taxes, insurance, and closing costs all affect what you can comfortably spend. And with everyday expenses continuing to compete for your paycheck, setting a realistic homebuying budget is more important than ever.
The good news? You do not need to be a financial expert to make a smart decision. By understanding your income, planning for additional expenses, and looking beyond the listing price, you can find a home that fits both your lifestyle and your finances.
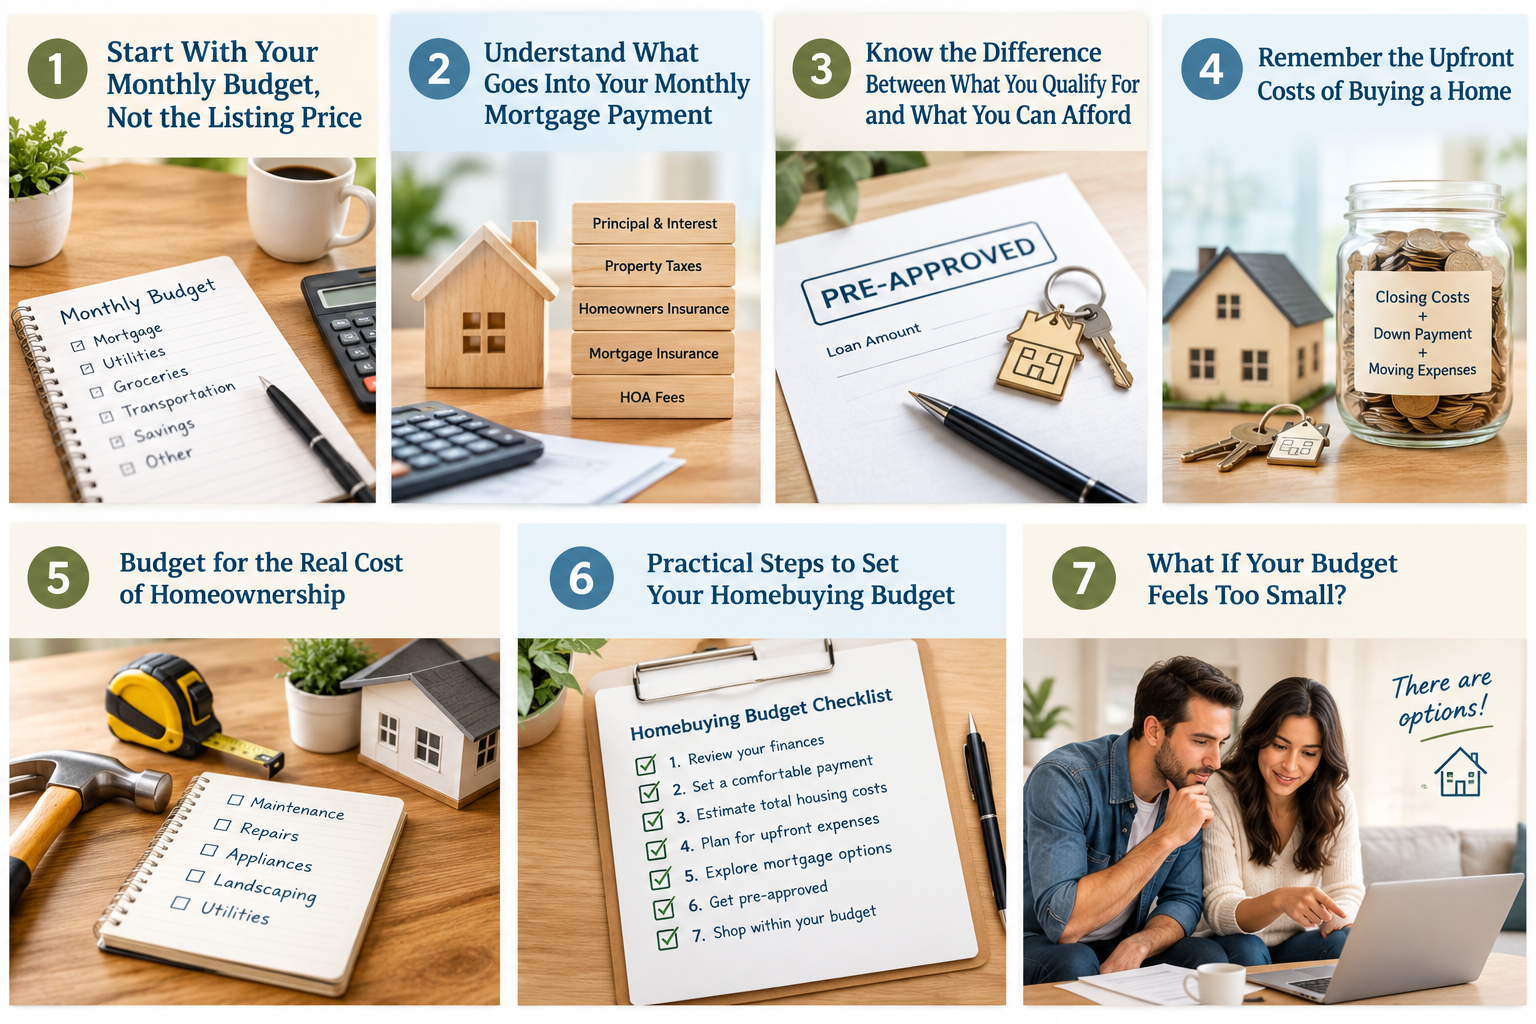
1. Start With Your Monthly Budget, Not the Listing Price
It is easy to begin your home search by looking at the maximum price you think you can afford. However, a better starting point is your monthly budget.
Think of your finances as a pie. Your mortgage payment is just one slice. You still need room for groceries, transportation, utilities, savings, entertainment, and unexpected expenses.
Start by calculating your monthly take-home pay. Then subtract your regular expenses, including:
Car payments, student loans, and credit card payments
Groceries, transportation, and utility bills
Childcare, subscriptions, and other recurring expenses
Retirement contributions and emergency savings
Personal spending and lifestyle costs
The money left over can help you determine how much you can comfortably put toward housing.
For example, if your household brings home $6,000 per month, you should not automatically assume that a $2,500 housing payment is affordable. Consider your other obligations and the amount you want to save each month before deciding on a comfortable payment.
The goal is to buy a home that supports your life, not one that consumes your entire paycheck.
2. Understand What Goes Into Your Monthly Mortgage Payment
When calculating how much house you can afford, remember that your monthly mortgage payment involves more than repaying the money you borrow.
Your total housing costs may include:
Principal and interest: The amount you repay on your mortgage and the cost of borrowing.
Property taxes: Taxes that help fund local services, schools, and public infrastructure.
Homeowners insurance: Coverage that helps protect your property against covered losses.
Mortgage insurance: An additional cost that may apply depending on your loan and down payment.
HOA fees: Monthly or annual fees if the property belongs to a homeowners association.
These expenses can vary significantly from one property to another, even when two homes have similar listing prices.
For instance, a home with a lower purchase price but higher property taxes may cost more each month than a slightly more expensive home in another area.
When comparing properties, look at the estimated total monthly housing payment rather than focusing on the mortgage alone. This gives you a clearer picture of what homeownership will actually cost.
3. Know the Difference Between What You Qualify For and What You Can Afford
Getting pre-approved for a mortgage is an important step in the homebuying process. It helps you understand how much a lender may be willing to lend based on your financial situation.
However, your mortgage pre-approval amount should be treated as a ceiling, not a spending target.
Lenders evaluate factors such as your income, credit history, existing debts, and other financial details. They may not fully account for every personal goal or expense that matters to you.
Perhaps you want to start a family, travel more, save for retirement, or build an emergency fund. Choosing a less expensive home may give you more freedom to pursue those goals.
Before deciding on your price range, ask yourself:
Can I comfortably make the payment every month?
Will I still have money for savings and emergencies?
Could I manage if my utility bills or insurance costs increased?
Would I be able to handle an unexpected home repair?
A home should provide stability, not constant financial stress.
4. Remember the Upfront Costs of Buying a Home
Your down payment is an important part of your homebuying budget, but it is not the only expense you need to prepare for.
Buyers may also need money for closing costs, inspections, appraisals, moving services, utility deposits, and immediate repairs or furnishings.
Closing costs vary by location, lender, and transaction. Your lender can provide a loan estimate to help you understand expected charges early in the process.
It is also worth remembering that a larger down payment is not always the best choice if it leaves you with little money in reserve.
For example, putting more money toward your home could reduce your loan amount and potentially lower your monthly payment. But if you use nearly all your savings to do so, an unexpected roof repair or medical bill could create financial pressure.
A practical approach is to plan for both your purchase expenses and an emergency fund. The right balance depends on your income, financial obligations, and comfort level.
5. Budget for the Real Cost of Homeownership
Renters generally contact their landlord when something goes wrong with the property. Homeowners, on the other hand, are usually responsible for maintenance and repairs.
That means your budget should include money for expenses that do not arrive on a predictable monthly schedule.
Consider costs such as:
Heating and cooling system maintenance
Plumbing repairs and appliance replacements
Roof, gutter, and exterior maintenance
Lawn care, snow removal, and landscaping
Higher utility bills during certain seasons
Think of your home like a car: even when everything runs smoothly, regular maintenance helps prevent bigger problems later.
Before purchasing, research the property's age, condition, and likely maintenance needs. A home inspection can help identify potential concerns, although it cannot predict every future repair.
If your budget is already tight, a property requiring significant immediate work may not be the best fit, even if the asking price looks attractive.
6. Practical Steps to Set Your Homebuying Budget
Ready to turn your numbers into a realistic price range? Follow these steps before scheduling your first home tour.
Step 1: Review your finances. Calculate your take-home income, monthly bills, existing debt, and current savings.
Step 2: Choose a comfortable housing payment. Decide how much you can spend each month while still covering your needs and maintaining your savings goals.
Step 3: Estimate the full housing cost. Include principal, interest, property taxes, homeowners insurance, applicable mortgage insurance, and HOA fees.
Step 4: Calculate your upfront funds. Account for your down payment, closing costs, moving expenses, and money for immediate repairs.
Step 5: Explore mortgage options. Compare loan programs, interest rates, down payment requirements, and estimated monthly payments. A mortgage professional can explain which options may suit your situation.
Step 6: Get pre-approved. Once you have a comfortable budget in mind, speak with a lender to understand your borrowing options.
Step 7: Search within your price range. Focus on homes that meet your needs without forcing you to sacrifice your financial security.
7. What If Your Budget Feels Too Small?
If the homes you like seem out of reach, you still have options. You may want to explore nearby neighborhoods, consider a smaller property, or look at homes that need only manageable cosmetic updates.
You could also spend time paying down high-interest debt, building your savings, or improving your credit profile before buying. Depending on your circumstances, researching eligible down payment assistance programs may also be worthwhile.
Avoid rushing into a purchase simply because you are worried that home prices will rise. Buying a home is a major financial commitment, and waiting until you are better prepared can be a sensible decision.
A knowledgeable real estate agent can help you compare neighborhoods, understand local property values, and identify homes that align with your budget and priorities.
Find a Home That Fits Your Life and Your Budget
Knowing how much house you can afford means looking beyond your mortgage approval or a property's asking price. It means understanding your monthly expenses, preparing for upfront costs, allowing room for repairs, and protecting your ability to save for the future.
With a realistic budget and the right guidance, you can approach your home search with greater confidence and make a decision that supports your long-term goals.
Ready to find a home that fits your budget and lifestyle? Start exploring properties at Home Onward. If you have questions or would like more information about your homebuying journey, email Tress Homes at tresshomes@gmail.com. The right home is not just one you can buy today. It is one you can comfortably enjoy for years to come.